Statement: USMI Statement on Proposed Mortgage Insurance Policy Changes

Seth Appleton, president of U.S. Mortgage Insurers, issued the below statement on proposed mortgage insurance policy changes announced by Director of Federal Housing (FHFA) Bill Pulte:

“USMI supports the work of Director Pulte and the Trump Administration to improve housing affordability. Private mortgage insurance helps homebuyers achieve the dream of homeownership without the need for a large cash down payment and it has become even more affordable in recent years with premium rates declining 25% or more since 2017, driven by robust competition in the market and lower corporate tax rates enacted during President Trump’s first term. Aligning Fannie Mae with Freddie Mac’s policy so servicers can proactively reach out to borrowers is an action that we support.

“In 2025 alone, private MI saved the average homebuyer $48,000 in cash due at the closing table. And, starting this year, the Working Families Tax Cuts Act restored the deductibility of private and government MI premiums for eligible households, making low down payment homeownership even more affordable.

For more information on the many benefits of private MI, including its temporary nature, please visit our website.”

USMI Welcomes VantageScore 4.0 Implementation by Fannie Mae and Freddie Mac

WASHINGTON Seth Appleton, President of U.S. Mortgage Insurers (USMI), today released the following statement:

“USMI and its members support the modernization of credit score models used by Fannie Mae and Freddie Mac and we welcome U.S. Federal Housing (FHFA) Director Pulte’s announcement that the GSEs will now accept VantageScore 4.0 from all single-family seller / servicers. USMI members insured loans scored with VantageScore 4.0 throughout the initial rollout, working closely with lender partners and the GSEs every step of the way.

“Modernized credit scoring helps promote expanded homeownership opportunities for creditworthy borrowers and prudent risk management for the housing finance system. We support Director Pulte’s work to expand access to credit scores that more accurately reflect a borrower’s credit profile; it is an important step toward making homeownership attainable for more Americans.

“We look forward to continuing our collaboration with FHFA, the GSEs, technology companies, and our lender partners to ensure a smooth rollout of this change and to support borrowers throughout the process.”

###

U.S. Mortgage Insurers (USMI) is dedicated to a housing finance system backed by private capital that enables access to housing finance for borrowers while protecting taxpayers. Mortgage insurance offers an effective way to make mortgage credit available to more people. USMI is ready to help build the future of homeownership. Learn more at www.usmi.org

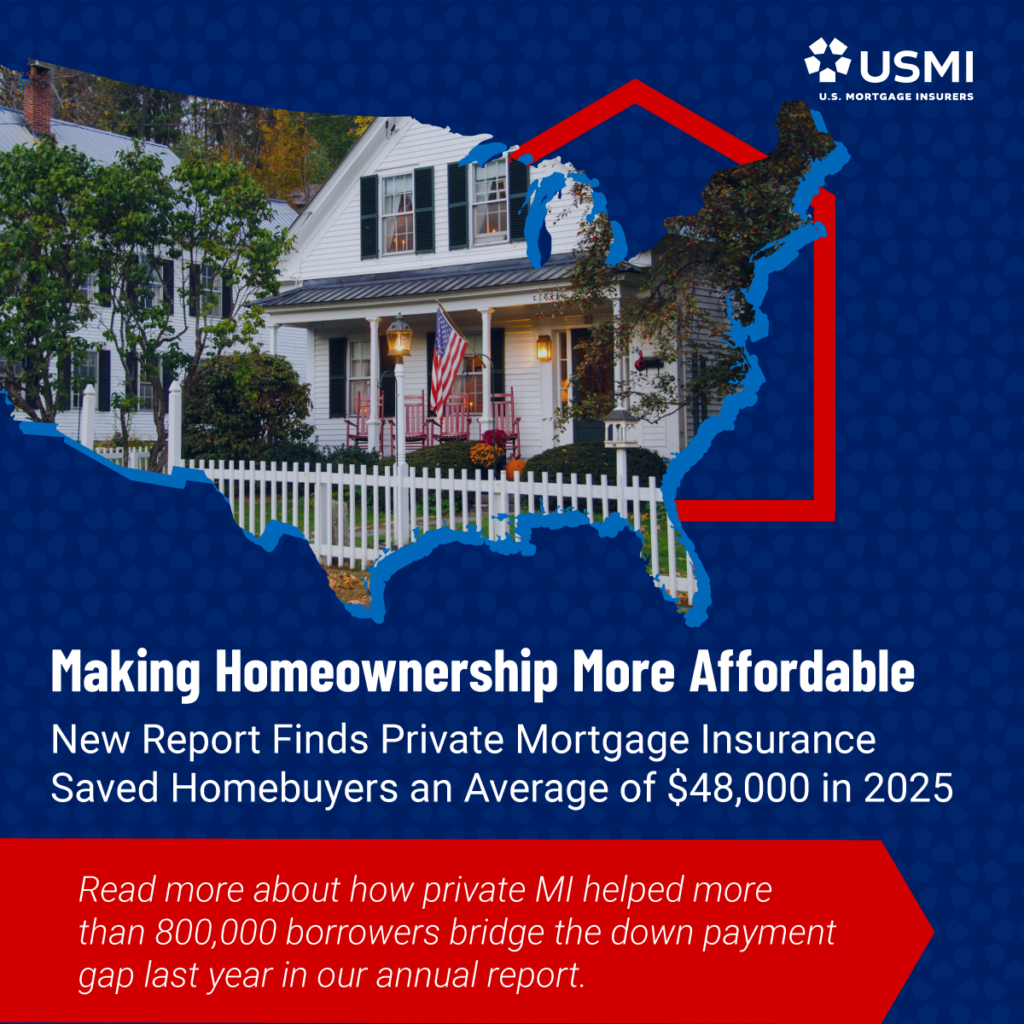
Making Homeownership More Affordable: New Report Finds Private Mortgage Insurance Saved Homebuyers an Estimated $48,000 in Closing Costs in 2025

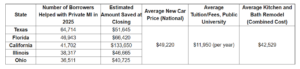
WASHINGTON, DC A new report released today by U.S. Mortgage Insurers (USMI) shows that private mortgage insurance (MI) helped more than 800,000 low down payment borrowers qualify for home financing in 2025. On average, these borrowers saved an estimated $48,000 in cash needed at closing compared to saving up for a 20% down payment – nearly enough to buy a new car, cover tuition and fees at the average public university, or remodel both a kitchen and bathroom. This allowed hundreds of thousands of households to become homeowners years sooner than would otherwise be possible.

Collectively, the report found that private MI has saved American homebuyers more than $285 billion in down payment costs since 2020, including more than $35.3 billion in 2025 alone. What’s more, publicly reported data confirm that the cost of private MI, as measured by in-force premium yields, has, in stark contrast to other costs of homeownership, declined 25% since 2017 – reaffirming that the small, temporary cost of monthly private MI paid by the borrower provides homebuyers, lenders, the government-sponsored enterprises (GSEs), and taxpayers with outsized benefits. The new report further details how private MI is strong and resilient private capital that provides stability to the housing market and broader financial system.

“Homeownership has been a cornerstone of the American Dream for 250 years and private mortgage insurance puts that dream within reach for hundreds of thousands of households,” said Seth Appleton, President of USMI. “This new report demonstrates the tremendous savings that private MI provides and underscores that it is a powerful financial tool that allows families to unlock homeownership years or even decades sooner than would otherwise be possible.”

National Trends
The new USMI report also found:

  • Over 800,000 households in 2025 used low down payment mortgages backed by private MI.
  • The average $48,000 saved in cash needed at closing is nearly the price of a new car (per Kelley Blue Book/Cox Automotive), covers roughly four years of tuition and fees at the average public in-state university ($11,950 per year, per the College Board), or is enough to remodel both a kitchen ($26,943 on average) and a bathroom ($15,586 on average), with money left over.
  • 64% of purchasers with private MI in 2025 were first-time homebuyers.
  • $376,317 was the average loan amount for a home purchase backed by private MI in 2025.
  • Saving for a 20% down payment could take the typical potential homebuyer 25 years.
  • The total value of mortgage originations supported by private MI in 2025 was more than $311 billion.
  • As of the end of 2025, the industry insured more than $1.6 trillion of mortgages, including $1.4 trillion of mortgages backed by Fannie Mae and Freddie Mac (the GSEs), protecting the housing finance system and taxpayers from credit risk.
  • The private MI industry has covered more than $62 billion in claims for losses since the 2008 financial crisis.
  • Nearly 41 million borrowers have benefited from private MI since 1957.

Top Five States Where Borrowers Used Private Mortgage Insurance in 2025

Texas, Florida, California, Illinois, and Ohio ranked as the top five states for mortgage financing with private MI in 2025. This is the third year in a row these states ranked in the top five for private MI use.
Why Use Private Mortgage Insurance?

Private MI helps low down payment borrowers access affordable mortgage financing while protecting the GSEs, lenders, investors, and taxpayers against risk. Private MI enables a borrower to qualify for mortgage financing with a down payment as low as 3%. Borrower-paid monthly private MI, the most commonly used form, is only a temporary cost for homebuyers, as it can be canceled or automatically terminates once the loan meets certain requirements.

Amassing a large cash down payment can be one of the biggest hurdles to homeownership, particularly for first-time buyers. Private MI allows borrowers – who are not able to put down 20% – to qualify for a conventional loan by insuring the lender against potential losses in the event the borrower is unable to repay the loan and there is not sufficient equity in the home to cover the amount owed. USMI’s 2024 Homeownership Market Survey found that while homeownership is very important to survey respondents, only one-third of them were aware that it is possible to qualify for financing with only 3% or 5% down.

A Second Round of Savings at Tax Time

Beginning next tax season, private MI carries additional benefits for qualifying homeowners thanks to the Working Families Tax Cuts which permanently reinstated the deductibility of private and government MI premiums for eligible homeowners. This action by Congress and President Trump means the return of a deduction that provides working-class homeowners with meaningful tax relief without increasing risk in the housing finance system. USMI has long advocated for the reinstatement of this deduction, which was claimed more than 44 million times for tax years 2007-2021, for a collective $64.7 billion in deductions. In 2021, the last year this deduction was available, qualifying homeowners received an average deduction of $2,364, according to IRS data. Additionally, the 2017 Tax Cuts & Jobs Act included cost savings that were passed on to low down payment homebuyers in the form of lower private MI premium rates.

Private Mortgage Insurance Protects Taxpayers

For nearly seven decades, private MI has served as the first layer of private capital protecting the housing finance system from unnecessary risk. Private MI is scalable and serves lenders of all sizes and business models, from the largest global institutions to the smallest community banks. It has also proven to be a reliable method for shielding the GSEs, lenders, investors, and taxpayers from losses, having paid $62 billion in claims since the 2008 financial crisis and housing market downturn. That’s $62 billion covered by private capital rather than taxpayers and the federal government. The private MI industry’s ability to employ risk-based pricing to granularly assess, price, and manage long-term mortgage credit risk also allows private MI companies to provide further protection to the GSEs and taxpayers.

The complete report is available here, along with fact sheets for all 50 states and the District of Columbia.

###

USMI is dedicated to a housing finance system backed by private capital that enables access to housing finance for borrowers while protecting taxpayers. Private mortgage insurance offers an effective way to make mortgage credit available to more people. USMI is ready to help build the future of homeownership. Learn more at www.usmi.org

Illinois Homebuyers 4th in Nation Using Private Mortgage Insurance in 2025, Saving an Average of $46,000 at Closing

WASHINGTON, DC —Illinois was fourth in the nation for homebuyers that used private mortgage insurance (MI) to purchase their homes in 2025, according to a new report released today from U.S. Mortgage Insurers (USMI). Over 38,000 Illinois households used private MI last year, with 70% of purchase loans going to first-time homebuyers, and Illinois was fourth in the nation for the ninth consecutive year in the number of borrowers who turned to private MI to purchase a home or refinance a loan with a down payment as low as 3%.

On average, Illinois borrowers using private MI saved an estimated $46,000 in cash needed at closing compared to saving up for a 20% down payment. This allowed thousands of Illinois households to purchase a home years sooner than would otherwise be possible. Nationally, more than 800,000 households became homeowners or refinanced a loan using private MI last year.

“Homeownership has been a cornerstone of the American Dream for 250 years, and private mortgage insurance puts that dream within reach for hundreds of thousands of households nationwide,” said Seth Appleton, President of USMI. “This new report demonstrates the tremendous savings that private MI provides to Illinois families and underscores that it is a powerful financial tool that allows families to unlock homeownership years or even decades sooner than would otherwise be possible.”

Illinois Trends
2025 data for Illinois showed that:

  • It could take an Illinois household earning the state median income ($84,210) 18 years to save for a 20% down payment (plus closing costs) for a $311,110 single-family home, the median sales price in Illinois. With a 5% down payment, the wait time decreases by 12 years.
  • $305,149 was the average loan amount for a home purchased with private MI in Illinois.
  • 70% of purchasers in Illinois with private MI in 2025 were first-time homebuyers.
  • For many Illinoisans, the biggest hurdle in buying a home is the 20% down payment that many Americans mistakenly believe is required for mortgage approval.

“In 2025, private MI helped homebuyers across Illinois enter into homeownership with down payments as low as 3%,” said Appleton. “Instead of delaying homeownership and waiting to save for a 20% cash down payment, more than 38,000 Illinoisans were able to put down roots and start building equity sooner thanks to the help of low down payment mortgages backed by private MI.”

Why Use Private Mortgage Insurance?

Private MI helps low down payment borrowers access affordable mortgage financing while protecting the GSEs, lenders, investors, and taxpayers against risk. Private MI enables a borrower to qualify for mortgage financing with a down payment as low as 3%. Borrower paid monthly private MI, the most commonly used form, is only a temporary cost for homebuyers, as it can be canceled or automatically terminates once the loan meets certain requirements.

Amassing a large cash down payment can be one of the biggest hurdles to homeownership, particularly for first-time buyers. Private MI allows borrowers – who are not able to put down 20% – to qualify for a conventional loan by insuring the lender against potential losses in the event the borrower is unable to repay the loan and there is not sufficient equity in the home to cover the amount owed. USMI’s 2024 Homeownership Market Survey found that while homeownership is very important to survey respondents, only one-third of them were aware that it is possible to qualify for financing with only 3% or 5% down.

Beginning next tax season, private MI carries additional benefits for qualifying homeowner thanks to the Working Families Tax Cuts which reinstated and made permanent the deductibility of MI premiums for eligible homeowners. This action by Congress and President Trump means the return of a deduction that provides working class homeowners with meaningful tax relief without increasing risk in the housing finance system. USMI has long advocated for the reinstatement of this deduction, which was claimed more than 44 million times for tax years 2007-2021, for a collective $64.7 billion in deductions. In 2021, the last year this deduction was available, more than 55,000 qualifying Illinois homeowners claimed the deduction, receiving an average deduction of $1,600 per household. Additionally, the 2017 Tax Cuts & Jobs Act included cost savings that were passed on to low down payment homebuyers in the form of lower private MI premium rates.

Private Mortgage Insurance Protects Taxpayers

For nearly seven decades, private MI has served as the first layer of private capital protecting the housing finance system from unnecessary risk. Private MI is scalable and serves lenders of all sizes and business models, from the largest global institutions to the smallest community banks. It has also proven to be a reliable method for protecting the GSEs, lenders, investors, and taxpayers from losses, having paid $62 billion in claims since the 2008 financial crisis and housing market downturn. That’s $62 billion covered by private capital rather than taxpayers and the federal government. The private MI industry’s ability to employ risk-based pricing to granularly assess, price, and manage long-term mortgage credit risk also allows private MI companies to serve as a second set of eyes when it comes to managing risk in the system, providing further protection to the GSEs and taxpayers.

The complete report is available here, along with fact sheets for Illinois, the other 49 states, and the District of Columbia.

###

USMI is dedicated to a housing finance system backed by private capital that enables access to housing finance for borrowers while protecting taxpayers. Private mortgage insurance offers an effective way to make mortgage credit available to more people. USMI is ready to help build the future of homeownership. Learn more at www.usmi.org.


Ohio Homebuyers 5th in Nation Using Private Mortgage Insurance in 2025, Saving an Average of $40,000 at Closing

WASHINGTON, DC —Ohio was fifth in the nation for homebuyers that used private mortgage insurance (MI) to purchase their homes in 2025, according to a new report released today from U.S. Mortgage Insurers (USMI). Over 36,000 Ohio households used private MI last year, with 67% of purchase loans going to first-time homebuyers, and Ohio was fifth in the nation for the fifth consecutive year in the number of borrowers who turned to private MI to purchase a home or refinance a loan with a down payment as low as 3%.

On average, Ohio borrowers using private MI saved an estimated $40,000 in cash needed at closing compared to saving up for a 20% down payment. This allowed thousands of Ohio households to purchase a home years sooner than would otherwise be possible. Nationally, more than 800,000 households became homeowners or refinanced a loan using private MI last year.

“Homeownership has been a cornerstone of the American Dream for 250 years, and private mortgage insurance puts that dream within reach for hundreds of thousands of households nationwide,” said Seth Appleton, President of USMI. “This new report demonstrates the tremendous savings that private MI provides to Ohio families and underscores that it is a powerful financial tool that allows families to unlock homeownership years or even decades sooner than would otherwise be possible.”

Ohio Trends
2025 data for Ohio showed that:

  • It could take an Ohio household earning the state median income ($80,520) 17 years to save for a 20% down payment (plus closing costs) for a $271,500 single-family home, the median sales price in Ohio. With a 5% down payment, the wait time decreases by 11 years.
  • $269,846 was the average loan amount for a home purchased with private MI in Ohio.
  • 67% of purchasers in Ohio with private MI in 2025 were first-time homebuyers.
  • For many Ohioans, the biggest hurdle in buying a home is the 20% down payment that many Americans mistakenly believe is required for mortgage approval.

“In 2025, private MI helped homebuyers across Ohio enter into homeownership with down payments as low as 3%,” said Appleton. “Instead of delaying homeownership and waiting to save for a 20% cash down payment, more than 36,000 Ohioans were able to put down roots and start building equity sooner thanks to the help of low down payment mortgages backed by private MI.”

Why Use Private Mortgage Insurance?

Private MI helps low down payment borrowers access affordable mortgage financing while protecting the GSEs, lenders, investors, and taxpayers against risk. Private MI enables a borrower to qualify for mortgage financing with a down payment as low as 3%. Borrower paid monthly private MI, the most commonly used form, is only a temporary cost for homebuyers, as it can be canceled or automatically terminates once the loan meets certain requirements.

Amassing a large cash down payment can be one of the biggest hurdles to homeownership, particularly for first-time buyers. Private MI allows borrowers – who are not able to put down 20% – to qualify for a conventional loan by insuring the lender against potential losses in the event the borrower is unable to repay the loan and there is not sufficient equity in the home to cover the amount owed. USMI’s 2024 Homeownership Market Survey found that while homeownership is very important to survey respondents, only one-third of them were aware that it is possible to qualify for financing with only 3% or 5% down.

Beginning next tax season, private MI carries additional benefits for qualifying homeowner thanks to the Working Families Tax Cuts which reinstated and made permanent the deductibility of MI premiums for eligible homeowners. This action by Congress and President Trump means the return of a deduction that provides working class homeowners with meaningful tax relief without increasing risk in the housing finance system. USMI has long advocated for the reinstatement of this deduction, which was claimed more than 44 million times for tax years 2007-2021, for a collective $64.7 billion in deductions. In 2021, the last year this deduction was available, more than 25,220 qualifying Ohio homeowners claimed the deduction, receiving an average deduction of $1,641 per household. Additionally, the 2017 Tax Cuts & Jobs Act included cost savings that were passed on to low down payment homebuyers in the form of lower private MI premium rates.

Private Mortgage Insurance Protects Taxpayers

For nearly seven decades, private MI has served as the first layer of private capital protecting the housing finance system from unnecessary risk. Private MI is scalable and serves lenders of all sizes and business models, from the largest global institutions to the smallest community banks. It has also proven to be a reliable method for protecting the GSEs, lenders, investors, and taxpayers from losses, having paid $62 billion in claims since the 2008 financial crisis and housing market downturn. That’s $62 billion covered by private capital rather than taxpayers and the federal government. The private MI industry’s ability to employ risk-based pricing to granularly assess, price, and manage long-term mortgage credit risk also allows private MI companies to serve as a second set of eyes when it comes to managing risk in the system, providing further protection to the GSEs and taxpayers.

The complete report is available here, along with fact sheets for Ohio, the other 49 states, and the District of Columbia.

###

USMI is dedicated to a housing finance system backed by private capital that enables access to housing finance for borrowers while protecting taxpayers. Private mortgage insurance offers an effective way to make mortgage credit available to more people. USMI is ready to help build the future of homeownership. Learn more at www.usmi.org.

Texas Homebuyers 1st in Nation Using Private Mortgage Insurance in 2025, Saving an Average of $51,000 at Closing

WASHINGTON, DC — More Texans used private mortgage insurance (MI) to purchase their homes than the residents of any other state in 2025, according to a new report released today from U.S. Mortgage Insurers (USMI). Over 64,000 Texan households used private MI last year, with 58% of purchase loans going to first-time homebuyers, and Texas led the nation for the ninth consecutive year in the number of borrowers who turned to private MI to purchase a home or refinance a loan with a down payment as low as 3%.

On average, Texan borrowers using private MI saved an estimated $51,000 in cash needed at closing compared to saving up for a 20% down payment. This allowed thousands of Texan households to purchase a home years sooner than would otherwise be possible. Nationally, more than 800,000 households became homeowners or refinanced a loan using private MI last year.

“Homeownership has been a cornerstone of the American Dream for 250 years, and private mortgage insurance puts that dream within reach for hundreds of thousands of households nationwide,” said Seth Appleton, President of USMI. “This new report demonstrates the tremendous savings that private MI provides to Texas families and underscores that it is a powerful financial tool that allows families to unlock homeownership years or even decades sooner than would otherwise be possible.”

Texas Trends
2025 data for Texas showed that:

  • It could take a Texan household earning the state median income ($81,490) 21 years to save for a 20% down payment (plus closing costs) for a $344,300 single-family home, the median sales price in Texas. With a 5% down payment, the wait time decreases by 14 years.
  • $381,333 was the average loan amount for a home purchased with private MI in Texas.
  • 58% of purchasers in Texas with private MI in 2025 were first-time homebuyers.
  • For many Texans, the biggest hurdle in buying a home is the 20% down payment that many Americans mistakenly believe is required for mortgage approval.

“In 2025, private MI helped homebuyers across Texas enter into homeownership with down payments as low as 3%,” said Appleton. “Instead of delaying homeownership and waiting to save for a 20% cash down payment, more than 64,000 Texans were able to put down roots and start building equity sooner thanks to the help of low down payment mortgages backed by private MI.”

Why Use Private Mortgage Insurance?

Private MI helps low down payment borrowers access affordable mortgage financing while protecting the GSEs, lenders, investors, and taxpayers against risk. Private MI enables a borrower to qualify for mortgage financing with a down payment as low as 3%. Borrower paid monthly private MI, the most commonly used form, is only a temporary cost for homebuyers, as it can be canceled or automatically terminates once the loan meets certain requirements.

Amassing a large cash down payment can be one of the biggest hurdles to homeownership, particularly for first-time buyers. Private MI allows borrowers – who are not able to put down 20% – to qualify for a conventional loan by insuring the lender against potential losses in the event the borrower is unable to repay the loan and there is not sufficient equity in the home to cover the amount owed. USMI’s 2024 Homeownership Market Survey found that while homeownership is very important to survey respondents, only one-third of them were aware that it is possible to qualify for financing with only 3% or 5% down.

Beginning next tax season, private MI carries additional benefits for qualifying homeowner thanks to the Working Families Tax Cuts which reinstated and made permanent the deductibility of MI premiums for eligible homeowners. This action by Congress and President Trump means the return of a deduction that provides working class homeowners with meaningful tax relief without increasing risk in the housing finance system. USMI has long advocated for the reinstatement of this deduction, which was claimed more than 44 million times for tax years 2007-2021, for a collective $64.7 billion in deductions. In 2021, the last year this deduction was available, more than 105,000 qualifying Texan homeowners claimed the deduction, receiving an average deduction of $2,069 per household. Additionally, the 2017 Tax Cuts & Jobs Act included cost savings that were passed on to low down payment homebuyers in the form of lower private MI premium rates.

Private Mortgage Insurance Protects Taxpayers

For nearly seven decades, private MI has served as the first layer of private capital protecting the housing finance system from unnecessary risk. Private MI is scalable and serves lenders of all sizes and business models, from the largest global institutions to the smallest community banks. It has also proven to be a reliable method for protecting the GSEs, lenders, investors, and taxpayers from losses, having paid $62 billion in claims since the 2008 financial crisis and housing market downturn. That’s $62 billion covered by private capital rather than taxpayers and the federal government. The private MI industry’s ability to employ risk-based pricing to granularly assess, price, and manage long-term mortgage credit risk also allows private MI companies to serve as a second set of eyes when it comes to managing risk in the system, providing further protection to the GSEs and taxpayers.

The complete report is available here, along with fact sheets for Texas, the other 49 states, and the District of Columbia.

###

USMI is dedicated to a housing finance system backed by private capital that enables access to housing finance for borrowers while protecting taxpayers. Private mortgage insurance offers an effective way to make mortgage credit available to more people. USMI is ready to help build the future of homeownership. Learn more at www.usmi.org
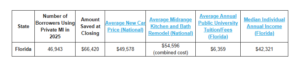
Florida Homebuyers 2nd in Nation Using Private Mortgage Insurance in 2025, Saving an Average of $66,000 at Closing

WASHINGTON, DC —Florida was second in the nation for homebuyers that used private mortgage insurance (MI) to purchase their homes in 2025, according to a new report released today from U.S. Mortgage Insurers (USMI). Over 46,000 Floridian households used private MI last year, with 58% of purchase loans going to first-time homebuyers, and Florida was second in the nation for the third consecutive year in the number of borrowers who turned to private MI to purchase a home or refinance a loan with a down payment as low as 3%.

On average, Floridian borrowers using private MI saved an estimated $66,000 in cash needed at closing compared to saving up for a 20% down payment. This allowed thousands of Floridian households to purchase a home years sooner than would otherwise be possible. Nationally, more than 800,000 households became homeowners or refinanced a loan using private MI last year.

“Homeownership has been a cornerstone of the American Dream for 250 years, and private mortgage insurance puts that dream within reach for hundreds of thousands of households nationwide,” said Seth Appleton, President of USMI. “This new report demonstrates the tremendous savings that private MI provides to Florida families and underscores that it is a powerful financial tool that allows families to unlock homeownership years or even decades sooner than would otherwise be possible.”

Florida Trends
2025 data for Florida showed that:

  • It could take a Floridian household earning the state median income ($75,630) 29 years to save for a 20% down payment (plus closing costs) for a $442,800 single-family home, the median sales price in Florida. With a 5% down payment, the wait time decreases by 19 years.
  • $396,845 was the average loan amount for a home purchased with private MI in Florida.
  • 58% of purchasers in Florida with private MI in 2025 were first-time homebuyers.
  • For many Floridians, the biggest hurdle in buying a home is the 20% down payment that many Americans mistakenly believe is required for mortgage approval.

“In 2025, private MI helped homebuyers across Florida enter into homeownership with down payments as low as 3%,” said Appleton. “Instead of delaying homeownership and waiting to save for a 20% cash down payment, more than 46,000 Floridians were able to put down roots and start building equity sooner thanks to the help of low down payment mortgages backed by private MI.”

Why Use Private Mortgage Insurance?

Private MI helps low down payment borrowers access affordable mortgage financing while protecting the GSEs, lenders, investors, and taxpayers against risk. Private MI enables a borrower to qualify for mortgage financing with a down payment as low as 3%. Borrower paid monthly private MI, the most commonly used form, is only a temporary cost for homebuyers, as it can be canceled or automatically terminates once the loan meets certain requirements.

Amassing a large cash down payment can be one of the biggest hurdles to homeownership, particularly for first-time buyers. Private MI allows borrowers – who are not able to put down 20% – to qualify for a conventional loan by insuring the lender against potential losses in the event the borrower is unable to repay the loan and there is not sufficient equity in the home to cover the amount owed. USMI’s 2024 Homeownership Market Survey found that while homeownership is very important to survey respondents, only one-third of them were aware that it is possible to qualify for financing with only 3% or 5% down.

Beginning next tax season, private MI carries additional benefits for qualifying homeowner thanks to the Working Families Tax Cuts which reinstated and made permanent the deductibility of MI premiums for eligible homeowners. This action by Congress and President Trump means the return of a deduction that provides working class homeowners with meaningful tax relief without increasing risk in the housing finance system. USMI has long advocated for the reinstatement of this deduction, which was claimed more than 44 million times for tax years 2007-2021, for a collective $64.7 billion in deductions. In 2021, the last year this deduction was available, more than 86,640 qualifying Floridian homeowners claimed the deduction, receiving an average deduction of $2,531 per household. Additionally, the 2017 Tax Cuts & Jobs Act included cost savings that were passed on to low down payment homebuyers in the form of lower private MI premium rates.

Private Mortgage Insurance Protects Taxpayers

For nearly seven decades, private MI has served as the first layer of private capital protecting the housing finance system from unnecessary risk. Private MI is scalable and serves lenders of all sizes and business models, from the largest global institutions to the smallest community banks. It has also proven to be a reliable method for protecting the GSEs, lenders, investors, and taxpayers from losses, having paid $62 billion in claims since the 2008 financial crisis and housing market downturn. That’s $62 billion covered by private capital rather than taxpayers and the federal government. The private MI industry’s ability to employ risk-based pricing to granularly assess, price, and manage long-term mortgage credit risk also allows private MI companies to serve as a second set of eyes when it comes to managing risk in the system, providing further protection to the GSEs and taxpayers.

The complete report is available here, along with fact sheets for Florida, the other 49 states, and the District of Columbia.

###

USMI is dedicated to a housing finance system backed by private capital that enables access to housing finance for borrowers while protecting taxpayers. Private mortgage insurance offers an effective way to make mortgage credit available to more people. USMI is ready to help build the future of homeownership. Learn more at www.usmi.org.

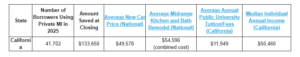
California Homebuyers 3rd in Nation Using Private Mortgage Insurance in 2025, Saving an Average of $133,000 at Closing

WASHINGTON, DC —California was third in the nation for homebuyers that used private mortgage insurance (MI) to purchase their homes in 2025, according to a new report released today from U.S. Mortgage Insurers (USMI). Over 41,000 Californian households used private MI last year, with 71% of purchase loans going to first-time homebuyers, and California was third in the nation for the third consecutive year in the number of borrowers who turned to private MI to purchase a home or refinance a loan with a down payment as low as 3%.

On average, Californian borrowers using private MI saved an estimated $133,000 in cash needed at closing compared to saving up for a 20% down payment. This allowed thousands of Californian households to purchase a home years sooner than would otherwise be possible. Nationally, more than 800,000 households became homeowners or refinanced a loan using private MI last year.

“Homeownership has been a cornerstone of the American Dream for 250 years, and private mortgage insurance puts that dream within reach for hundreds of thousands of households nationwide,” said Seth Appleton, President of USMI. “This new report demonstrates the tremendous savings that private MI provides to California families and underscores that it is a powerful financial tool that allows families to unlock homeownership years or even decades sooner than would otherwise be possible.”

California Trends
2025 data for California showed that:

  • It could take a Californian household earning the state median income ($100,600) 44 years to save for a 20% down payment (plus closing costs) for a $891,000 single-family home, the median sales price in California. With a 5% down payment, the wait time decreases by 29 years.
  • $578,398 was the average loan amount for a home purchased with private MI in California.
  • 71% of purchasers in California with private MI in 2025 were first-time homebuyers.
  • For many Californians, the biggest hurdle in buying a home is the 20% down payment that many Americans mistakenly believe is required for mortgage approval.

“In 2025, private MI helped homebuyers across California enter into homeownership with down payments as low as 3%,” said Appleton. “Instead of delaying homeownership and waiting to save for a 20% cash down payment, more than 41,000 Californians were able to put down roots and start building equity sooner thanks to the help of low down payment mortgages backed by private MI.”

Why Use Private Mortgage Insurance?

Private MI helps low down payment borrowers access affordable mortgage financing while protecting the GSEs, lenders, investors, and taxpayers against risk. Private MI enables a borrower to qualify for mortgage financing with a down payment as low as 3%. Borrower paid monthly private MI, the most commonly used form, is only a temporary cost for homebuyers, as it can be canceled or automatically terminates once the loan meets certain requirements.

Amassing a large cash down payment can be one of the biggest hurdles to homeownership, particularly for first-time buyers. Private MI allows borrowers – who are not able to put down 20% – to qualify for a conventional loan by insuring the lender against potential losses in the event the borrower is unable to repay the loan and there is not sufficient equity in the home to cover the amount owed. USMI’s 2024 Homeownership Market Survey found that while homeownership is very important to survey respondents, only one-third of them were aware that it is possible to qualify for financing with only 3% or 5% down.

Beginning next tax season, private MI carries additional benefits for qualifying homeowner thanks to the Working Families Tax Cuts which reinstated and made permanent the deductibility of MI premiums for eligible homeowners. This action by Congress and President Trump means the return of a deduction that provides working class homeowners with meaningful tax relief without increasing risk in the housing finance system. USMI has long advocated for the reinstatement of this deduction, which was claimed more than 44 million times for tax years 2007-2021, for a collective $64.7 billion in deductions. In 2021, the last year this deduction was available, more than 171,820 qualifying Californian homeowners claimed the deduction, receiving an average deduction of $3,047 per household. Additionally, the 2017 Tax Cuts & Jobs Act included cost savings that were passed on to low down payment homebuyers in the form of lower private MI premium rates.

Private Mortgage Insurance Protects Taxpayers

For nearly seven decades, private MI has served as the first layer of private capital protecting the housing finance system from unnecessary risk. Private MI is scalable and serves lenders of all sizes and business models, from the largest global institutions to the smallest community banks. It has also proven to be a reliable method for protecting the GSEs, lenders, investors, and taxpayers from losses, having paid $62 billion in claims since the 2008 financial crisis and housing market downturn. That’s $62 billion covered by private capital rather than taxpayers and the federal government. The private MI industry’s ability to employ risk-based pricing to granularly assess, price, and manage long-term mortgage credit risk also allows private MI companies to serve as a second set of eyes when it comes to managing risk in the system, providing further protection to the GSEs and taxpayers.

The complete report is available here, along with fact sheets for California, the other 49 states, and the District of Columbia.

###

USMI is dedicated to a housing finance system backed by private capital that enables access to housing finance for borrowers while protecting taxpayers. Private mortgage insurance offers an effective way to make mortgage credit available to more people. USMI is ready to help build the future of homeownership. Learn more at www.usmi.org.

Factsheet: What Others Are Saying About MI in Bank Capital Rules

Financial institutions and stakeholder groups agree that recognizing private mortgage insurance (MI) in the proposed bank capital rules is critical to serving creditworthy borrowers without access to large down payments. Dozens of commenters on the proposed rules advocated for recognizing private MI in calculating a mortgage’s LTV ratio for risk-weighting purposes. Here’s just some of what they had to say:


  • “The agencies should recognize private mortgage insurance when calculating LTV for risk-weighting purposes, subject to an appropriate counterparty haircut, to avoid regressively disadvantaging first-time and first-generation homebuyers.” – National Housing Conference (NHC)


  • “However, the proposal may disadvantage creditworthy borrowers with limited funds for a large down payment because banks are likely to charge more for high-LTV loans. This price increase will disproportionately impact first-time and low- and moderate-income home buyers who already face increased challenges due to the lack of affordable housing and limited supply.” – National Association of Homebuilders (NAHB)


  • “WBA also supports several targeted refinements raised more specifically in other industry comment letters, including reconsideration of the risk weight applied to mortgage servicing assets, explicit recognition of private mortgage insurance as a credit risk mitigant, and a closer look at the operational risk add-on embedded within the standardized approach’s mortgage and corporate risk weights.” – Wisconsin Bankers Association (WBA)


  • “We recommend that PMI be credited in the calculation of risk weights for first-lien, owner-occupied bank mortgage exposures in light of the aforementioned changes in the mortgage insurance industry since the financial crisis, the statistical evidence demonstrating the credit risk reduction afforded by mortgage insurance, and the fact that mortgage insurance is recognized as a significant credit risk mitigant by the GSEs and their federal regulator.” – Housing Policy Council (HPC)


  • “Without the acknowledgement of the role of PMI and its potential to avoid losses, banks are further incentivized to avoid providing high-LTV loans, often to the market segments that need it most.” – National Association of REALTORS®


  • “PMI provides effective credit protection on higher LTV mortgages, reducing loss severity on loans where borrower equity is limited… ICBA believes that PMI provides sound credit protection for mortgage loans originated for sale in the secondary market as well as those retained in a bank’s portfolio. From a policy perspective, it is reasonable to recognize that PMI meaningfully reduces loss severity on higher LTV loans—often to levels comparable to those observed on lower LTV exposures.” – Independent Community Bankers of America (ICBA)


  • “Under the Proposals, a high LTV loan would be assigned an elevated risk weight even if a substantial portion of the credit risk is transferred to a private mortgage insurer through PMI. The borrower thereby effectively pays for the same risk twice: once in PMI premiums and again through the higher cost of capital passed through by the bank…The Agencies have requested comment on whether the rule should recognize the risk mitigating effect of PMI for RRE exposures, and MBA strongly recommends that they do so. The post-Great Financial Crisis capital and regulatory regime governing the private mortgage insurance industry supports recognition of PMI. Recognizing PMI or equivalent credit enhancement such as readily marketable collateral provides depository institutions with appropriate incentives to reach first-time and underserved homebuyers who cannot make a 20% down payment.” – Mortgage Bankers Association (MBA)


  • “The FHLBanks also support the recognition of Private Mortgage Insurance (“PMI”) as a significant risk mitigant that should be factored into calculations of risk-weighted assets.” – Council of Federal Home Loan Banks


  • “The proposed new risk weighting would make it substantially more costly for banks to originate high-LTV loans, resulting in fewer home purchase options for low- and moderate income families.” – National Council of State Housing Agencies (NCSHA)


  • “By excluding PMI as a mitigating factor in determining risk weights, it may result in capital requirements that overstate economic risk. In particular, the framework’s reliance on gross LTV without adjustment for PMI coverage may fail to capture the reduction in loss severity achieved through insurance protection. As a result, the Proposed Rule may weaken the economic incentive to originate loans supported by PMI—despite its demonstrated role in absorbing losses—and create a disconnect between regulatory capital requirements and the true risk profile of insured residential mortgage assets.” – BayCoast Bank


  • “The exclusion of PMI from the risk-weighting framework overstates credit risk on loans with high loan-to-value (LTV) ratios that are otherwise supported by strong credit enhancements. This exclusion reduces the economic incentive to originate loans with PMI, despite its demonstrated role in loss mitigation circumstances and loan performance. This also creates inconsistency between regulatory capital treatment and the actual risk profile of insured mortgage assets.” – First Mutual Holding Co.


  • “In addition, the agencies may wish to consider explicit recognition of private mortgage insurance as a credit risk mitigant, supported by empirical evidence demonstrating reduced loss severity.” – Valley National Bancorp & Valley National Bank


  • “Excluding PMI from the LTV calculation understates the risk mitigation already present in many mortgage portfolios and may discourage banks from requiring PMI on higher-LTV originations, which is a counterproductive outcome from a safety and soundness perspective.” – Axos Bank


  • “Gateway supports explicit recognition of private mortgage insurance in the calculation of the LTV ratio used to determine risk weights, subject to appropriate eligibility standards… The alternative of ignoring PMI entirely is inconsistent with the actual economic risk reduction provided by the insurance and disadvantages community banks that originate responsibly underwritten high‐LTV loans to first‐time homebuyers.” – Gateway First Bank


  • “Getting this calibration correct is paramount – a framework that acknowledges PMI’s risk-mitigating role for safety and soundness purposes but ignores it for capital purposes leaves capital requirements misaligned with the actual risk profile of insured mortgage exposures.” – Fifth Third Bank

Comment Letter on “Enterprise Duty to Serve Underserved Markets”

On July 24, USMI submitted a comment letter in response to the U.S. Federal Housing (FHFA) Notice of Proposed Rulemaking (NPR) on “Enterprise Duty to Serve Underserved Markets.” USMI supports FHFA’s consideration of advances in manufactured housing and the opportunity to better serve homebuyers who purchase it. Additionally, USMI recommends that FHFA incorporate private MI and primary first-loss credit enhancement into the safety and soundness evaluation for any new product or activity to ensure that homebuyers are affordably and sustainably served, while private capital absorbs credit losses. Click here to read the full letter.

USMI Statement on Introduction of the Sustainable Homeownership Act (H.R. 9460)

WASHINGTON Seth Appleton, President of U.S. Mortgage Insurers (USMI), today released the following statement regarding the introduction of H.R. 9460, the “Sustainable Homeownership Act,” by Rep. Scott Fitzgerald (WI-05):

“We applaud Rep. Fitzgerald’s thoughtful approach and are pleased to support H.R. 9460, which includes important policies to advance access to affordable home financing for creditworthy borrowers nationwide, while promoting safety and soundness in the housing finance system.

“Among its key provisions, H.R. 9460 would ensure that private capital continues to meaningfully reduce the loss severity of low down payment loans that default, absorbing risk ahead of lenders, the government-sponsored enterprises, and taxpayers; foster transparency around new products, activities, and pilots; and prohibit piggyback mortgages, which allow borrowers to take out multiple loans for the same home purchase and performed poorly during the Great Financial Crisis.

“For nearly 70 years, the private MI industry has served first-time and working-class homebuyers throughout the country who don’t have the resources for 20% down payments and USMI’s members help hardworking Americans buy homes sooner throughout all housing market cycles. We commend Rep. Fitzgerald for his efforts to make homeownership more attainable and sustainable, while ensuring that private capital – not the taxpayer – continues to bear a greater share of mortgage credit risk.”

###

U.S. Mortgage Insurers (USMI) is dedicated to a housing finance system backed by private capital that enables access to housing finance for borrowers while protecting taxpayers. Mortgage insurance offers an effective way to make mortgage credit available to more people. USMI is ready to help build the future of homeownership. Learn more at www.usmi.org.